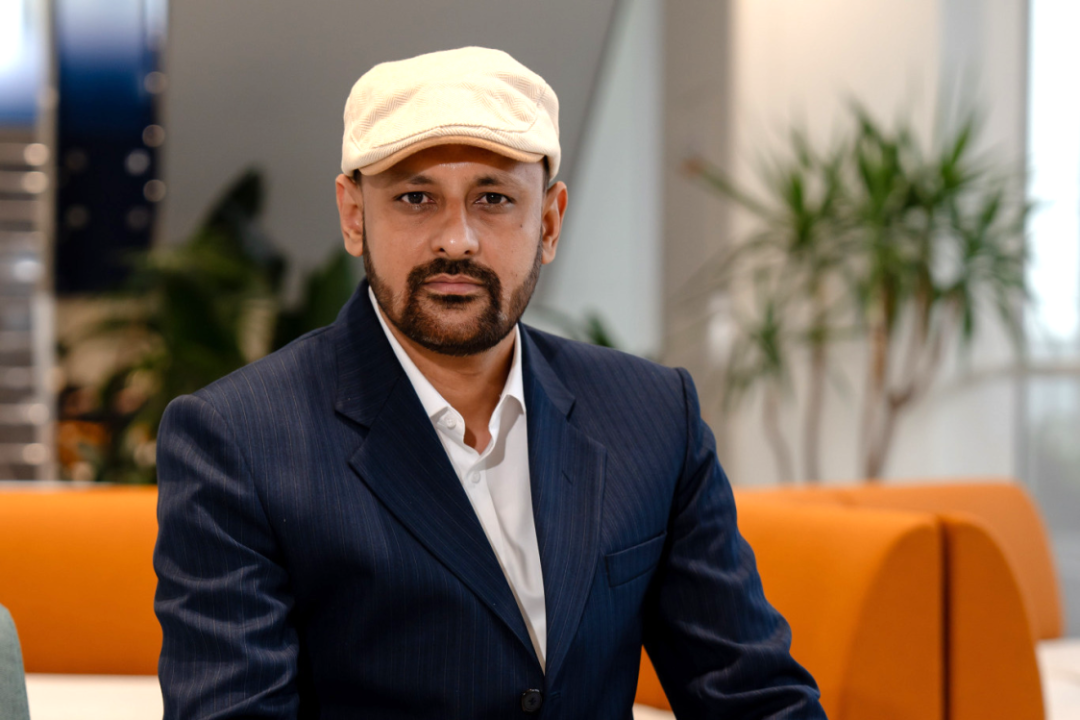

Guo Liu, PHD
-
Position:Assistant Professor of Mathematical Sciences
-
College:College of Science, Mathematics and Technology
-
Office:CSMT 546
-
E-mail:
EDUCATIONAL BACKGROUND
B.S. in Mathematics, The Chinese University of Hong Kong
M.S. in Actuarial Science, The University of Melbourne
Ph.D. in Actuarial Science, The University of Melbourne
ACADEMIC EXPERIENCE
Wenzhou-Kean University, Aug 2025-present, Assistant Professor, Department of Mathematical Sciences
Swansea University, Mar 2023-Aug 2025, Lecturer, Department of Mathematics
The University of Melbourne, Feb 2022-Dec 2022, Sessional Lecturer, Centre for Actuarial Studies, Department of Economics
BIOGRAPHY
Prof. Liu was born in Sichuan Province, China. He finished his high school in Sichuan and was awarded a full scholarship in 2011 to study Mathematics at The Chinese University of Hong Kong, where he earned a Bachelor’s degree with honors. In 2016, based on outstanding academic performance, Prof. Liu received the International Graduate Merit Scholarship to pursue a Master’s degree in Actuarial Science at the University of Melbourne. He successfully obtained the degree and was named to the Dean’s Honors List. He also passed all the examinations of the Foundation Program of the Institute of Actuaries of Australia. In 2018, Prof. Liu was awarded the Australian Government Research Training Program (RTP) Scholarship to continue his studies at the University of Melbourne, pursuing a Ph.D. in Actuarial Science under the supervision of Prof. Shuanming Li and Prof. Zhuo Jin. His research focused on the application of stochastic optimal control in actuarial modeling and pricing. To date, he has published over ten papers in internationally renowned journals such as the European Journal of Operational Research, Insurance: Mathematics and Economics, etc. He has delivered presentations and reports at multiple international academic conferences in the field of actuarial science and has actively engaged in academic exchanges and collaborations with renowned scholars. Prof. Liu has achieved systematic research results in the fields of stochastic optimal control and actuarial modeling and pricing, demonstrating strong academic influence and international academic exchange capabilities. In terms of academic research, his exceptional scientific research abilities have led to a series of high-level research achievements, earning high recognition from peers both domestically and internationally. His research contributions have not only advanced the discipline but have also generated broad impact within the international academic community.
RESEARCH INTEREST
Stochastic Optimal Control, Stochastic Analysis, Financial Mathematics, Point Processes, Actuarial Science, Machine Learning
COURSES TAUGHT
MATH 2400 Calc for Bus and Eco
MATH 2526 Applied Statistics
MATH 3560 Applied Regression Analysis
MATH 3700 Big Data Computing
MATH 4890 Senior Seminar
SELECTED PUBLICATIONS
-
Zhang, P., Liu, G., & Zhang, J. (2026). Stochastic asset allocation and reinsurance strategies for an ambiguity-averse insurer under a generalized contagion risk framework. Scandinavian Actuarial Journal, 1-36.
-
Liu, G., & Jang, J. (2026). Optimal asset allocation and reinsurance problem under enhanced dynamic contagion processes. Annals of Actuarial Science, 20(1), 166-209.
-
Zhang, P., Zhang, J., Liu, G., & Li, J. (2025). Contract design under an enhanced dynamic contagious process. Journal of Computational and Applied Mathematics, 117266.
-
Cheung, E. C., Liu, G., Woo, J. K., Zhang, J., & Zhu, D. (2025). Optimal periodic strategies with dividends payable from gains only. Insurance: Mathematics and Economics, 103203.
-
Feng, Y., Jang, J., Li, S., & Liu, G. (2025). Robust risk sharing and reinsurance contract design for contagious catastrophe and secondary claims under principal–agent framework. International Review of Financial Analysis, 108, 104646.
-
Liu, G., Feng, Y., & Wang, Z. (2025). Equilibrium Investment and Reinsurance Strategies in a Contagion Model with External Common Shock Dependence Under Smooth Ambiguity. Available at SSRN 5382244.
-
Liu, G., Jin, Z., & Li, S. (2024). Optimal dividend policy with self-exciting claims in the Gamma–Omega model. Finance Research Letter, 106162.
-
Liu, G., Jin, Z., Li, S., & Zhang, J. (2022). Stochastic asset allocation and reinsurance game under contagious claims. Finance Research Letter, 49, 103123.
-
Liu, G., Jin, Z., & Li, S. (2021). Optimal investment, consumption, and life insurance strategies under a mutual-exciting contagious market. Insurance: Mathematics and Economics, 101(B), 508-524.
-
Liu, G., Jin, Z., & Li, S. (2021). Household lifetime strategies under a self-contagious market. European Journal of Operational Research, 288(3), 935-952.
-
Jin, Z., Liu, G., & Yang, H. (2020). Optimal consumption and investment strategies with liquidity risk and lifetime uncertainty for Markov regime-switching jump diffusion models. European Journal of Operational Research, 280(3), 1130-1143.
GRANTS
2026 青年科学基金项目(NSFC, C类)
2026 SSpF Research Program, WKU, China
Faculty Start-up Research Grant, WKU, China
Early Career Researchers Starter Grants, Swansea University, UK